Don’t expect to see sports prediction markets take Canada by storm in the same way that they exploded in prominence in the U.S.
Federal Canadian regulators issued a staff notice on Thursday that clarified their position that sports prediction markets should not be allowed under the securities or derivatives legislation that governs financial trading.
The Canadian Securities Administrators (CSA) and the Canadian Investment Regulatory Organization (CIRO) posted the public notice to explicitly state their views on sports event contracts “in light of growing interest in prediction markets in Canada.”
CSA staff’s view is that Event Contracts based on sports and entertainment events or outcomes should not be regulated within securities and derivatives legislation.
The CSA and CIRO
CIRO staff do not consider it appropriate to facilitate or approve an application by their dealer members to trade these types of Event Contracts.
The regulators added that while yes-no binary event contracts may fall within the broad federal definitions of securities or derivatives in general, certain categories “are outside the scope of that framework, or are otherwise excluded.” As well as sports and entertainment, the agencies are assessing whether other prediction markets categories should be excluded.
The CSA is the council of Canadian provincial securities regulators and the body that coordinates regulation for financial markets in the country. CIRO is the national self-regulatory organization that oversees investment dealers, mutual fund dealers, and trading activity, and has the authority to approve companies to allow Canadians to access prediction markets for trading.
CGA: Sports betting belongs to the provinces
In a statement on Thursday, the Canadian Gaming Association (CGA) commended the CSA and CIRO for clarifying their stance and drawing “a clear and sensible line” in the sand between what is and is not allowed.
Key context here is that the Criminal Code of Canada gives provincial governments the right to regulate gambling products, including sports betting. Ontario and Alberta have opted to open up their gambling markets by licensing commercial operators, while the other provinces maintain that their respective government-owned and operated platform is the only legal one in their jurisdiction.
“The CGA has long held that sports wagering, in whatever form it takes, should be offered only through provincial gaming regulators, and that the framework governing a product should be determined by what it does, not by what it is called,” added the CGA statement. “Today’s guidance affirms that principle, as CSA and CIRO have drawn a clear and sensible line: the distinction between a sports contract and a sports bet should not be reduced to semantics.”
“Sports wagering is sports betting, whatever the platform, and it belongs within the framework that provinces have built specifically to regulate it.”
CGA President and CEO Paul Burns
In its own statement on Thursday, one provincial government gaming operator, Loto-Québec, used the prediction markets notice as an opportunity to stress that while the popularity of sports event contracts has grown significantly in North America, “this form of betting is not legal in Québec.”
The CGA’s statement added that Canada’s gaming industry and provincial gaming regulators have built a network of consumer safeguards and player protections over the years. Veteran gaming lawyer Ron Segev told Canadian Gaming Business that aspect should not be overlooked, and opined that the federal financial regulators are not equipped to mitigate and combat gambling harms.
“I think it’s good and important that they came out with this reminder to the industry and I agree with their position,” said Segev, a founding partner at Segev LLP and a member of the firm’s Securities Practice Group. “We see the public harm that can arise by conflating gambling with investing or offering gambling-style products without proper responsible gambling measures and policies in place.
“The CSA and CIRO know they are not the correct agencies to deal with these public harm issues (as relates to gambling) but are the right agencies to protect investors (as relates to hyper-short-term binary options). I think they have the right bums in the right seats on this one.”
Companies like Kalshi and Wealthsimple are strictly limited
To date, only two CIRO dealer member firms have received approval from that regulator to facilitate access to prediction markets: Wealthsimple and Interactive Brokers Canada.
Wealthsimple unveiled a partnership with Kalshi in June and launched a new Wealthsimple Predict platform that hosts approximately 4,000 of Kalshi’s event contracts.
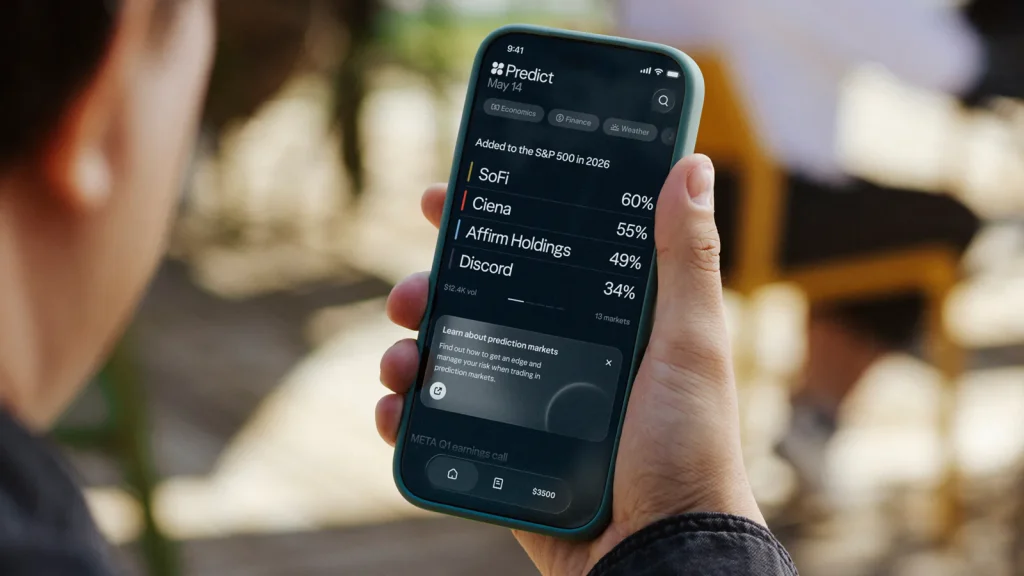
However, that product looks very different from what’s on offer on numerous federally approved platforms including Kalshi’s own site in the U.S. That’s because CIRO’s rules lay out various terms and conditions. Notably, these include restrictions such as:
- Only allowing prediction markets that take 30 days or longer to resolve.
- Only allowing select categories for trading, namely environmental forecasts, financial markets, and economic indicators. As well as sports and entertainment, other categories including election contracts are forbidden on CIRO-authorized platforms.
- Stipulating that all contracts that meet those requirements must be traded on and cleared through certain U.S. Commodity Futures Trading Commission-regulated exchanges and clearinghouses.
Now, the CSA and CIRO have gone beyond CIRO’s existing terms of service for members by formally stating their joint view that sports and entertainment prediction markets should not be classified as securities or derivatives products in general.
CSA and CIRO warn everyone to play by the rules
This is not the first public notice that the CSA and CIRO have issued addressing prediction markets in recent times.
In early April, a few days after announcing Wealthsimple’s CIRO approval, the two entities released a joint statement in which they stressed that while CIRO approval allows companies to facilitate Canadian access to event contracts, no prediction market has been recognized as an exchange, registered as a dealer, or exempted from those requirements by the CSA.
“CIRO’s position is clear: prediction-market products are not entitled to enter Canadian markets simply because they exist elsewhere,” a CIRO spokesperson told Canadian Gaming Business in June.
The regulators warned in April that “failure to comply with applicable requirements under Canadian securities and derivatives laws may lead to enforcement action.”
Canadian regulators have held prediction markets operators to account in the past for breaking the rules on event contracts. Most notably, Polymarket settled with the CSA member Ontario Securities Commission in 2025 after the company admitted it violated Ontario’s version of the Binary Options Ban, which prohibits the advertising, offering, selling or trading of short-term yes/no event contracts.
Polymarket was banned from operating in Ontario for two years as part of the settlement. It has remained active in other parts of Canada, although it quietly updated its terms of service in July to state that it no longer allowed access from Alberta, British Columbia, or Quebec, as well as Ontario.
Wealthsimple wants sports contracts allowed
The CSA and CIRO’s statement on sports prediction markets comes just a few weeks after Wealthsimple seemed to argue that sports contracts should be allowed on its platform.
In an Aug. 4 whitepaper, Wealthsimple executives called for the 30-day rule for binary options to be lifted, and argued that moving prediction markets on sports outcomes under gaming legislation and regulation would be “unworkable”.
“We believe it is appropriate for bilateral sports betting, where a gaming operator sets the odds and takes the other side of the bet, to be regulated under gaming laws, while sports event contracts that are traded and cleared by regulated derivatives market intermediaries to be regulated under securities laws,” wrote Wealthsimple.